Whether you’re a general contractor, electrician, plumber, roofer, or remodeler, having insurance is an important part of protecting your business. Many contractors start with General Liability Insurance because it is often required by clients, property owners, and project contracts. While this coverage is essential, it may not be enough to fully protect your business from the risks you face every day.
Understanding what General Liability Insurance covers—and what it doesn’t—can help you make informed decisions about your insurance needs.
What Does General Liability Insurance Cover?
General Liability Insurance helps protect contractors from certain common claims that can arise while performing work. This coverage may help pay for expenses related to:
- Third-party bodily injury
- Property damage caused to others
- Legal defense costs for covered claims
- Certain advertising or personal injury claims
For example, if a visitor trips over equipment at a job site and is injured, General Liability Insurance may help cover medical expenses and legal costs associated with the claim.
While this coverage is an important foundation, it does not protect against every risk a contractor may encounter.
Risks General Liability Insurance Doesn’t Cover
Many contractors are surprised to learn that General Liability Insurance has limitations. Depending on your operations, additional coverage may be necessary to protect your business from significant financial losses.
Employee Injuries
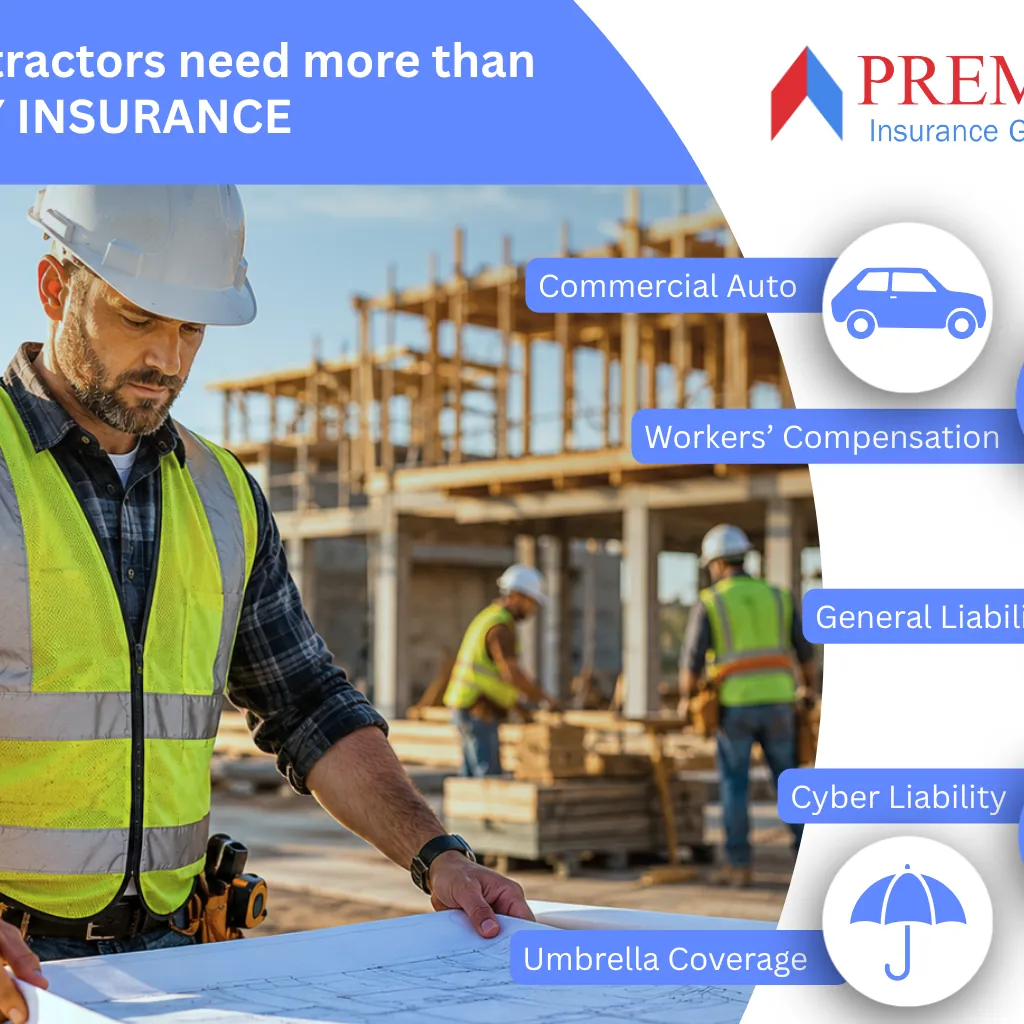
Construction and trade work often involve physical labor, heavy equipment, ladders, power tools, and potentially hazardous environments. If an employee is injured while performing job duties, General Liability Insurance typically will not cover the claim. Workers’ Compensation Insurance is designed to help cover medical expenses, rehabilitation costs, and lost wages for employees who suffer work-related injuries or illnesses.
Business Vehicle Accidents
If your business uses trucks, vans, or other vehicles to transport tools, equipment, or employees, personal auto insurance may not provide coverage for business-related accidents. Commercial Auto Insurance can help protect your business if a company vehicle is involved in an accident, causing property damage or bodily injury.
Major Lawsuits
In today’s environment, legal settlements and judgments can quickly exceed the limits of a standard liability policy. A serious accident involving significant injuries could result in expenses that go far beyond your primary coverage. Commercial Umbrella Insurance provides an additional layer of liability protection above the limits of certain underlying policies, helping safeguard your business from catastrophic losses.
Cyber Risks
Many contractors rely on digital tools for scheduling, invoicing, project management, payroll, and customer communication. Unfortunately, cybercriminals increasingly target businesses of all sizes. A cyberattack, ransomware incident, or data breach can disrupt operations and create costly recovery expenses. Cyber Liability Insurance may help businesses manage the financial impact of these events.
Building a Strong Insurance Foundation
Every contracting business is different, but many contractors benefit from a combination of coverages that work together to provide broader protection. Depending on your business, your insurance program may include:
- General Liability Insurance
- Workers’ Compensation Insurance
- Commercial Auto Insurance
- Commercial Umbrella Insurance
- Cyber Liability Insurance
The right combination depends on factors such as the size of your business, the services you provide, the number of employees you have, and the projects you undertake.
Why Insurance Reviews Matter
As your business grows, your insurance needs may change. Taking on larger projects, hiring additional employees, purchasing new equipment, or expanding into new service areas can all affect your risk exposure. Regular insurance reviews can help ensure your coverage keeps pace with your business and helps identify potential gaps before they become costly problems.
Protect Your Contracting Business with Confidence
General Liability Insurance is an important starting point, but it is only one piece of a comprehensive risk management strategy. Contractors face a variety of risks that may require additional protection beyond a standard liability policy.
At Premier Insurance Group LLC, we work with contractors and business owners to help them find insurance solutions tailored to their specific needs. Whether you’re just starting your business or looking to review your current coverage, our team can help you explore options designed to protect what you’ve worked hard to build.
Contact Premier Insurance Group LLC today to learn more about insurance solutions for contractors and request a personalized quote. Call us: +1-703-880-8800 DM us: +1 (703) 468 1012 Visit us: 8780 Centreville Road, suite 203 Manassas, VA 20110
This article is for general information only and isn’t legal or insurance advice. Coverage depends on your policy and carrier.